The 2026 Water and Wastewater M&A Picture: Two Buyer Pools, Not One
The market for acquirers of water and wastewater equipment distributors and rep agencies in 2026 consists of two parallel lanes with almost no overlap in deal logic. Lane one is the industrial-channel consolidator, a distribution or platform business that buys other distributors and rep agencies to pick up OEM principals, end-market geography, and a municipal or industrial customer base. Lane two is the infrastructure-asset private operator, a long-life water utility or fund-backed platform that buys treatment plants, concessions, and operating companies to own regulated or contract-based cash flow.
Two 2026 signals define each lane. On the industrial-channel side, Tencarva Machinery Company announced on 2026-04-22 the acquisition of WWaterTech Services, Inc., a Texas- and Oklahoma-focused water and wastewater rep agency representing approximately 60 OEMs, in a deal covered by naw.org/MDM (2026-04-22). On the infrastructure-asset side, Seven Seas Water Group, backed by EQT, publicly describes itself as one of the most active private acquirers of water and wastewater treatment infrastructure in the Western Hemisphere on its acquisitions page (sevenseaswater.com). A sales director or rep owner mapping the 2026 buyer universe must score both pools separately, as the asset brought to market determines which lane will look at it.
Tencarva Machinery: The Industrial-Channel Roll-Up to Watch in 2026
Tencarva Machinery Company is the most clearly documented industrial-channel roll-up of 2026, with two announced acquisitions in roughly ten weeks. The company is a flow control and process equipment distributor based in Greenville, NC, and is backed by Bessemer Investors, LLC, according to naw.org/MDM (2026-04-22). On MDM's 2025 Top Distributors Lists, Tencarva Machinery ranked No. 43 in the Industrial Supplies category (naw.org/MDM, 2026-04-22).
The first 2026 deal, announced in February, was the acquisition of Hoffman-Kane Distributors, Inc., a fluid-power distributor operating in Western Pennsylvania, Eastern Ohio, and West Virginia (naw.org/MDM, 2026-04-22). The second 2026 deal, announced 2026-04-22, was WWaterTech Services, Inc., a representative agency for water and wastewater equipment manufacturers and system suppliers serving municipal end markets in Texas and Oklahoma (naw.org/MDM, 2026-04-22). WWaterTech represents a comprehensive portfolio of water and wastewater process equipment from approximately 60 unique vendors; the firm was founded in 2006, is headquartered in Waller, TX, and is led by President and Owner Steve Holt, with 15-year executive Wes Holt set to take over as branch manager (naw.org/MDM, 2026-04-22).
Henry Ritchie, President of Tencarva, framed the WWaterTech deal as part of a strategy to grow and diversify Tencarva's municipal presence across the U.S., citing Texas as a premier municipal market and highlighting the strength of WWaterTech's OEM relationships (naw.org/MDM, 2026-04-22). These two 2026 deals define a target profile: a regional rep agency or specialty distributor with established OEM relationships, a defensible municipal or industrial end market, and a leadership team willing to stay through a transition. The WWaterTech structure—Steve Holt moving gradually into an advisory role, Wes Holt stepping up as branch manager—reflects the continuity Tencarva builds into its acquisition narrative (naw.org/MDM, 2026-04-22).
Seven Seas Water Group and EQT: The Infrastructure-Asset Buyer Pool
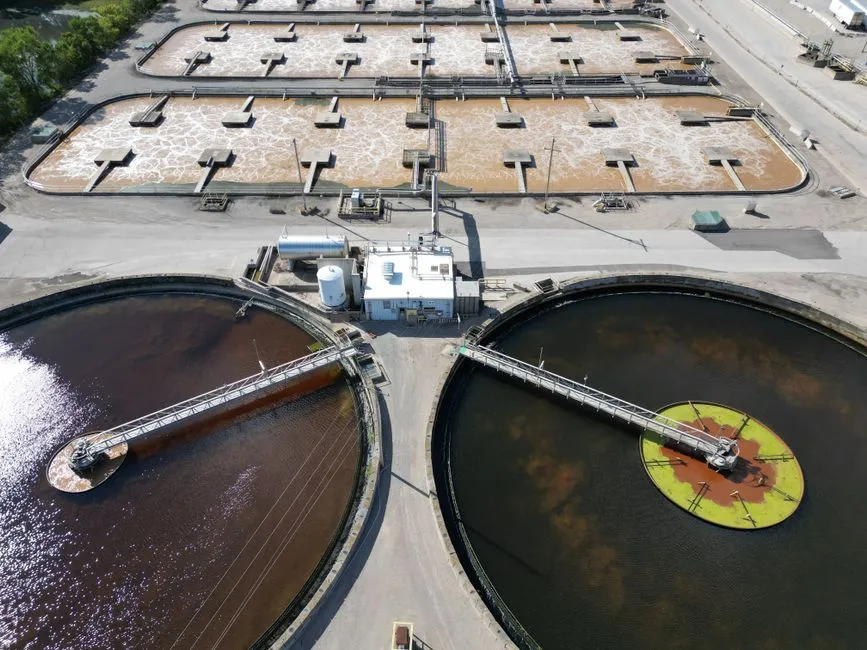
Seven Seas Water Group is the primary public marker for the infrastructure-asset pool in 2026. According to its acquisitions page, Seven Seas is one of the most active private acquirers of water and wastewater treatment infrastructure in the Western Hemisphere and is backed by EQT, a global infrastructure investment organization (sevenseaswater.com). The company is headquartered in Tampa, FL, with additional offices in Houston, TX, and directs acquisition inquiries to [email protected] (sevenseaswater.com).
The asset-class scope Seven Seas publishes provides a template for the infrastructure-asset buyer pool. It includes seawater and brackish-water reverse-osmosis facilities serving governmental, municipal, and industrial customers in coastal and island markets; decentralized and centralized wastewater treatment operations, including MBR and conventional activated-sludge systems, across commercial and municipal applications; multi-site portfolios of water and wastewater assets from operators, PE owners, or utilities seeking to divest a collection of facilities; public water and wastewater systems accessed via public-private partnership, concession, or asset sale; water purification, process water, high-purity water, and municipal and industrial wastewater treatment systems serving industrial or hospitality customers divesting non-core infrastructure; and private water and wastewater treatment companies acquired for platform and growth acceleration (sevenseaswater.com). Seven Seas specifically targets private water and wastewater treatment companies where an acquisition can accelerate growth and provide access to its platform, capital, and operating expertise (sevenseaswater.com).
For a sales director at an equipment manufacturer, this pool is relevant even if the company itself is not for sale. The underlying platforms specify equipment and choose OEMs for the plants they acquire, so a single Seven Seas-style transaction can open or close multi-plant supply relationships. Seven Seas also states it is often interested in assets with clear operational upside, as well as those requiring upgrades or facing compliance challenges (sevenseaswater.com), signaling that compliance-driven retrofit demand is a key component of 2026 deal logic.
Side-by-Side: Who Buys What in the 2026 Water and Wastewater Channel
The table below consolidates published data regarding the two buyer pools. The Tencarva column is drawn from naw.org/MDM coverage dated 2026-04-22; the Seven Seas column is drawn from the company's acquisitions page at sevenseaswater.com.
| Dimension | Industrial-channel acquirer (Tencarva pattern) | Infrastructure-asset acquirer (Seven Seas / EQT pattern) |
|---|---|---|
| Headquarters / capital base | Greenville, NC; backed by Bessemer Investors, LLC (naw.org/MDM, 2026-04-22) | Tampa, FL and Houston, TX; backed by EQT (sevenseaswater.com) |
| Target asset | Regional equipment distributor or rep agency with established OEM principals (e.g., WWaterTech, ~60 OEMs, Texas/Oklahoma municipal focus; Hoffman-Kane, fluid power, PA/OH/WV) (naw.org/MDM, 2026-04-22) | Treatment plants, MBR/activated-sludge systems, RO facilities, multi-site portfolios, PPP concessions, and operating companies (sevenseaswater.com) |
| Deal rationale stated publicly | "Grow and diversify Tencarva's municipal presence across the U.S."; reach into Texas municipal market and high-quality OEM relationships (naw.org/MDM, 2026-04-22) | Long-term ownership, operational stewardship, "Water-as-a-Service®" deployment, and upgrade of aging infrastructure (sevenseaswater.com) |
| Geographic emphasis | U.S. regional; 2026 footprint expansion in Texas/Oklahoma and Western PA/Eastern OH/WV (naw.org/MDM, 2026-04-22) | Western Hemisphere, with explicit comfort in coastal, island, and remote geographies (sevenseaswater.com) |
| What they pay for | OEM-relationship depth, installed municipal base, and seller continuity (Steve Holt advisory transition, Wes Holt branch manager role) (naw.org/MDM, 2026-04-22) | Operating track record, asset condition, regulatory familiarity, and growth potential; explicit interest in assets "requiring upgrades or facing compliance challenges" (sevenseaswater.com) |
| What an OEM or rep should bring to a first conversation | OEM count, revenue mix by principal, end-market concentration, leadership transition plan | Asset condition summary, regulatory status, capital-improvement backlog, and growth or compliance thesis |
A rep agency or specialty distributor is a fit for the Tencarva-style pool, while a treatment plant, operating company, or PPP-concession asset is a fit for the Seven Seas-style pool. There is no public 2026 ranking of PE-backed water infrastructure roll-ups comparable to the industrial-channel coverage in MDM, so the Seven Seas profile should be treated as illustrative rather than an exhaustive list of buyers in that lane.
How Equipment Manufacturers and Reps Should Approach Each Buyer Pool
The two pools prioritize different criteria, and preparing for both in parallel shortens the acquisition timeline. For the industrial-channel pool, the materials to assemble are OEM-relationship depth, an installed municipal or industrial base, and a clean leadership-handoff plan; the WWaterTech transition illustrates the continuity narrative a Tencarva-style buyer screens for (naw.org/MDM, 2026-04-22). For the infrastructure-asset pool, the materials are operating track record, regulatory familiarity, asset condition, and a clear growth or compliance thesis; Seven Seas explicitly states interest in assets with clear operational upside or those requiring upgrades (sevenseaswater.com).
The practical recommendation is a two-track outreach: route rep-agency and specialty-distributor conversations toward Tencarva-style acquirers, and route plant-level, operating-company, and PPP opportunities toward Seven Seas-style acquirers via [email protected] (sevenseaswater.com). Sellers in either lane should be ready to provide qualitative inputs: revenue mix, OEM count, end-market and geographic concentration, leadership-transition plan, and asset condition or compliance backlog. Deal multiples, EBITDA ranges, and earn-out structures are not disclosed in public research and must be requested directly from the buyer. For a wider read on demand drivers shaping 2026, the 2026 circular water economy outlook covers the policy and technology context that both buyer pools are responding to.
Frequently Asked Questions
Who is the most active acquirer of water and wastewater equipment distributors in 2026?
Tencarva Machinery Company is the most clearly documented 2026 acquirer of water and wastewater distributors and rep agencies, with two announced deals: WWaterTech Services, Inc. on 2026-04-22 and Hoffman-Kane Distributors, Inc. in February 2026, both reported by naw.org/MDM (2026-04-22). Tencarva is based in Greenville, NC, and is backed by Bessemer Investors, LLC.
How does a rep agency or specialty distributor get on a Tencarva-style buyer's shortlist?
Prepare a short brief that documents OEM-principal count, revenue mix by principal and end market, the geography covered, and a leadership-continuity plan for the post-close period; the WWaterTech handoff to Wes Holt as branch manager is the type of continuity story this pool screens for (naw.org/MDM, 2026-04-22). Approach through a written introduction that frames the business against Tencarva's stated municipal-presence strategy.
What does an infrastructure-asset buyer like Seven Seas actually purchase?
Seven Seas Water Group, backed by EQT, targets seawater and brackish-water reverse-osmosis facilities, MBR and conventional activated-sludge wastewater systems, multi-site asset portfolios, public water and wastewater systems via PPP, concession or asset sale, and private water and wastewater treatment companies acquired for platform growth (sevenseaswater.com). Inquiries go to [email protected].
Should a manufacturer that only sells equipment bother tracking infrastructure-asset buyers?
Yes, because infrastructure-asset platforms specify the equipment and choose the OEMs for the plants they acquire, meaning a single transaction in this lane can open or close multi-plant supply relationships. Seven Seas explicitly targets assets requiring upgrades or facing compliance challenges (sevenseaswater.com), which translates directly into retrofit and replacement demand for OEMs positioned on the bidder list.